An early mortgage payoff can sound straightforward: pay more than required and finish the loan sooner. The decision becomes more useful when the goal is translated into actual numbers.
Before committing extra cash to the mortgage, homeowners should know what they owe today, how long the current schedule has left, what their required principal-and-interest payment is, and how a proposed extra amount could change the projected payoff date and total interest. They should also know how much accessible cash would remain after making that commitment.
Those calculations do not tell a homeowner what they must do. They make the tradeoffs visible.
A broader Mortgage Payoff Strategy provides the framework for deciding how the mortgage fits with household cash flow and other priorities. This article focuses on the numbers to calculate before choosing an early-payoff target.
1. Start With the Current Principal Balance
The first number to identify is the current principal balance.
Principal is the amount of the mortgage that remains unpaid. It is not necessarily the same as the original loan amount, the total of future scheduled payments, or the amount needed to satisfy the loan on a particular future date.
The current principal balance gives homeowners a clean starting point for modeling an early payoff. It can usually be found on the latest mortgage statement or through the servicer’s online account.
Record the balance together with the date of the statement. Mortgage balances change as scheduled payments are credited, so a figure from several months ago may not accurately represent the loan today.
For planning purposes, this number answers a basic question: how much mortgage principal remains before any new payoff approach begins?
It also helps homeowners avoid using the home’s purchase price, original mortgage amount, or estimated home value as a substitute for the actual balance. Those figures may be relevant to other financial questions, but they do not show how much principal is currently owed.
2. Know the Difference Between Current Balance and Payoff Amount
If the goal is to estimate what it would take to eliminate the mortgage completely on a particular date, the current principal balance may not be enough.
A mortgage payoff amount is the amount required to fully satisfy the loan as of a specified date. It can differ from the current principal balance because it may include interest owed through the payoff date and certain unpaid fees or charges. Depending on the loan terms, a prepayment penalty may also be relevant.
Homeowners considering a full payoff can request an official payoff statement from their lender or servicer rather than assuming that the principal balance shown online is the final amount due.
For a longer-term early-payoff plan, the current principal balance is still useful for modeling. Keeping the two figures separate prevents a common error: treating today’s displayed balance as the exact amount required to close the loan.
Label the current balance and any official payoff amount with the date associated with each figure.
3. Calculate the Remaining Term and Baseline Payment Schedule
Next, determine how much time remains on the mortgage under the current schedule.
Do not assume the remaining term from the original loan length alone. A 30-year mortgage that began several years ago no longer has a 30-year remaining term. The starting point should be the number of scheduled payments or years still left today.
Then identify the required monthly principal-and-interest payment. If the total mortgage payment also includes taxes, homeowners insurance, mortgage insurance, or other escrow items, separate those amounts before modeling payoff scenarios.
This creates a baseline: what happens if nothing changes?
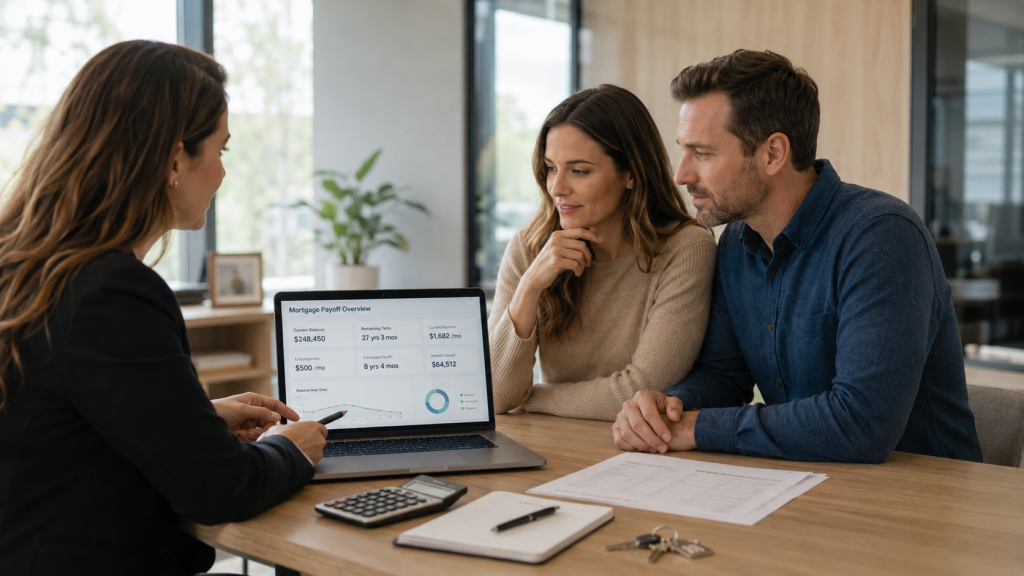
Write down the remaining number of payments, required principal-and-interest payment, current principal balance, and interest rate. An early-payoff scenario is only meaningful when it can be compared with the existing schedule.
The purpose is not to prove that early payoff is always the right choice. It is to show what the proposed change actually does.
4. Estimate the Interest Remaining Under the Current Schedule
The interest rate alone does not tell homeowners how many dollars of interest remain to be paid.
For planning, it is useful to estimate the future interest under the existing mortgage schedule. An amortization schedule or mortgage calculation can show how each future principal-and-interest payment is divided and provide an estimate of total interest remaining if the loan continues as scheduled.
This is a baseline estimate, not a promise. The calculation depends on the loan terms and the assumptions entered.
Homeowners should be careful not to confuse several different figures:
- The stated mortgage interest rate
- The dollar amount of interest in an individual payment
- Estimated interest remaining over the current schedule
- The official payoff amount on a specific date
Each answers a different question.
For an early mortgage payoff decision, compare the estimated interest remaining under the current schedule with the estimate under the proposed accelerated schedule, using the same starting balance, rate, and date.
The goal here is simply to establish a baseline for comparison.
5. Put a Dollar Amount on the Proposed Extra Payment
An early-payoff goal becomes easier to evaluate once the proposed additional payment is expressed as an actual dollar commitment.
Instead of saying, “I want to pay more each month,” calculate the amount being considered and what that represents over a year.
For example, if a homeowner is considering an additional $300 each month, that represents $3,600 of additional cash directed toward the mortgage over 12 months if every planned payment is made.
The annual figure matters because monthly amounts can feel smaller in isolation. Seeing the full-year commitment makes it easier to compare the mortgage goal with other uses for the same cash.
Calculate:
Proposed monthly extra amount × 12 = planned annual extra mortgage amount
For occasional payments, total only the amounts realistically expected during the year.
The objective is to convert an early-payoff idea into a measurable commitment that can be tested against the rest of the numbers.
6. Calculate the Revised Payoff Timeline and Interest Estimate
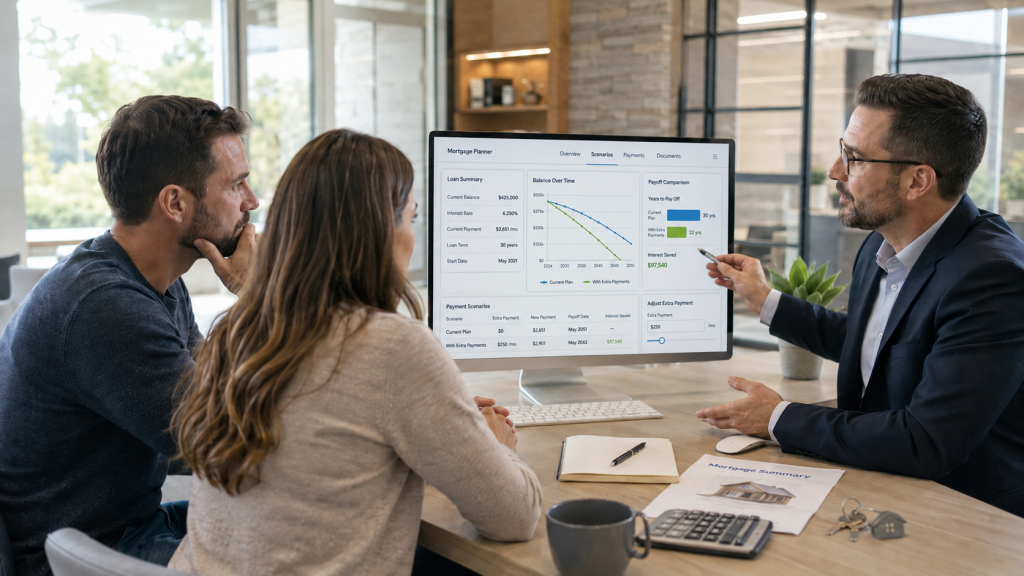
Once the baseline and proposed extra amount are known, compare the original schedule with the proposed early-payoff scenario.
The two outputs most homeowners will want to examine are:
- Estimated new payoff date
- Estimated total interest under the new schedule
Then calculate the difference between the baseline and the proposed scenario.
For the timeline:
Current projected payoff date − revised projected payoff date = estimated time shortened
For interest:
Estimated remaining interest under current schedule − estimated interest under revised schedule = estimated interest difference
These are projections, not guarantees. They assume the mortgage terms remain applicable and that the homeowner continues making the payments entered into the calculation.
This is also where precision matters. Avoid relying on a general statement that a particular extra payment “saves X years” unless the figure was calculated from the homeowner’s actual mortgage data.
A mortgage calculator or amortization tool can make these comparisons easier when the correct information is entered. If the numbers change later, rerun the calculation rather than continuing to rely on an old projection.
The useful outcome is a realistic scenario that shows what the household would have to contribute to produce the projected change.
7. Calculate What Remains After the Extra Payment
The mortgage calculation should not stop with the loan.
Before committing to the proposed amount, calculate what remains in the household budget after the extra mortgage payment is made.
A simple planning calculation is:
Monthly usable cash flow − proposed extra mortgage payment = cash flow remaining
Then compare the remaining amount with savings needs, irregular household expenses, planned repairs, insurance costs, and other financial priorities.
The goal is not to establish a universal minimum reserve. Households have different expenses, responsibilities, and risk tolerances. The calculation is useful because it shows whether the proposed mortgage amount leaves enough flexibility for the homeowner’s own situation.
It may also reveal that the first number considered is too aggressive. Reducing the proposed extra amount and rerunning the payoff projection can show how a more manageable payment changes the timeline.
This is where early-payoff planning becomes a decision rather than an assumption.
A homeowner can compare the mortgage benefit with the cash commitment required to create it. If the projected timeline looks attractive but the remaining monthly flexibility feels too limited, the calculation has still done its job by identifying that tradeoff before the money is committed.
Frequently Asked Questions
What numbers should I gather before calculating an early mortgage payoff?
Start with the current principal balance, interest rate, required principal-and-interest payment, remaining loan term, and current payment schedule. Then identify the additional amount being considered and the household cash flow available to support it.
Is my mortgage payoff amount the same as my principal balance?
No, not necessarily. The current principal balance shows unpaid principal, while an official payoff amount is the amount required to fully satisfy the mortgage as of a particular date. The payoff amount can include interest through that date and certain fees or charges.
How do I estimate how much earlier my mortgage could be paid off?
Compare the current payment schedule with a calculation that uses the same balance and interest rate but includes the proposed additional payment. The difference between the two projected payoff dates shows the estimated amount of time shortened.
Should I calculate interest savings before paying a mortgage off early?
Yes, it can be useful to compare estimated remaining interest under the current schedule with the estimated interest under the proposed early-payoff scenario. Treat the difference as a projection based on the assumptions entered, not a guaranteed savings amount.
What if the extra payment leaves too little cash available each month?
Rerun the calculation with a smaller additional amount. An early-payoff projection should be considered alongside savings needs, household expenses, and other financial priorities rather than evaluated only by how quickly the mortgage could end.
Early mortgage payoff becomes easier to evaluate when the decision is reduced to specific numbers instead of a vague goal.
Know the current principal balance. Distinguish it from an official payoff amount. Establish the remaining term and baseline payment schedule. Estimate the interest remaining, define the proposed additional payment, compare the revised payoff timeline, and calculate how much household cash remains after the change.
Those figures will not make the decision for a homeowner, but they make the consequences of the decision easier to see.
For the broader planning framework, review United Financial Freedom’s Mortgage Payoff Strategy resource and use the calculations above to evaluate an early-payoff scenario based on your own mortgage and cash flow.