Wanting to pay off a mortgage faster is understandable. The challenge is knowing what to change without relying on generic advice, optimistic examples, or someone else’s mortgage numbers.
A faster payoff starts with a clear picture of the loan and the household cash flow supporting it. Before increasing payments, homeowners should know the remaining principal balance, interest rate, required payment, available reserves, and how much money is realistically left after normal expenses.
That is the difference between guessing and following a plan. A structured mortgage payoff strategy gives homeowners a framework for deciding what they can change, what they should protect, and how to review progress over time.
Start With the Mortgage You Have Today
Before choosing any early-payoff approach, collect the numbers that describe the mortgage as it exists now.
Review the current principal balance, interest rate, required monthly payment, remaining loan term, and recent mortgage statements. If taxes and insurance are included in the monthly payment, separate those amounts from the principal-and-interest portion so it is easier to see what is actually reducing the loan balance.
This baseline matters because a mortgage cannot be evaluated accurately from the monthly payment alone. Two homeowners may make similar payments while having different balances, rates, remaining terms, and household budgets.
It is also useful to review the loan documents or contact the mortgage servicer before sending additional money. Homeowners who intend an extra amount to reduce principal should confirm how that payment will be applied and whether any loan terms affect early payments.
The goal at this stage is not to choose a tactic. It is to understand the starting point well enough to make the next decision deliberately.
Decide What Paying It Off Faster Means to You
“Pay off the mortgage faster” can mean different things.
One homeowner may want to shorten a 30-year repayment period by several years. Another may want to make steady progress without committing to a large monthly increase. Someone else may simply want to use occasional extra cash more intentionally.
Each goal can lead to a different plan.
Before choosing a payment amount, define the outcome you are trying to influence. Are you trying to reduce the balance more quickly, create a shorter projected payoff period, reduce long-term interest costs, or simply make better use of available cash?
A clear goal also makes it easier to recognize when an approach is too aggressive. If the plan requires a payment that leaves little room for normal household expenses or savings, the faster timeline may not be practical.
A useful mortgage payoff plan should make the goal clearer without turning that goal into a guaranteed date or result. The numbers can show possible scenarios, but the household still needs enough flexibility to respond when financial circumstances change.
Find the Cash Flow the Plan Can Actually Use
A mortgage payoff plan depends on cash flow. That means the next step is not asking, “How much extra can I send this month?” It is asking, “How much money is consistently available after the rest of the household is taken care of?”
Review several months of income and expenses rather than relying on one unusually good month. Include recurring bills as well as costs that appear less often, such as insurance premiums, home repairs, vehicle maintenance, medical expenses, school costs, annual subscriptions, and other irregular obligations.
This helps separate truly available cash from money that only looks available because a future expense has not arrived yet.
The amount used for a faster payoff does not have to be the maximum amount a household could possibly send. In many cases, a smaller amount that fits normal cash flow may be easier to sustain than an aggressive payment that regularly has to be reversed or skipped.
Cash flow can also change. A raise, reduced expense, paid-off obligation, or new household cost can affect what is available. A useful plan leaves room for those changes instead of assuming the same payment will always make sense.
Protect Savings and Other Financial Priorities
Paying down a mortgage creates equity, but equity is not the same as cash that is immediately available for an unexpected expense.
Homeowners still need to consider emergency savings, insurance deductibles, property taxes, home maintenance, healthcare, transportation, retirement planning, and other financial priorities. Directing too much money toward the mortgage can reduce flexibility elsewhere.
That does not mean homeowners should avoid early payoff. It means mortgage reduction should be considered alongside the rest of the financial plan.
Before increasing payments, ask whether enough accessible money remains for likely and unexpected needs. A strategy that works only when nothing goes wrong is difficult to maintain.
This is especially important for newer homeowners. The first several years of homeownership can bring expenses that were not obvious at closing, from repairs and maintenance to changes in insurance and property-related costs.
A sustainable approach should help reduce the mortgage without making the household less prepared for everything else that comes with owning a home.
Use Additional Payments Intentionally
Additional payments can help reduce a mortgage balance sooner when they are applied to principal, but sending extra money should be a deliberate part of the plan.
Homeowners should confirm how their servicer handles additional amounts and check statements afterward to make sure payments were credited as expected. The timing and amount of extra principal can affect the remaining loan differently, so assumptions based on another person’s mortgage may not apply.
There are several ways homeowners may choose to direct extra funds toward a mortgage, but the detailed mechanics of those methods are less important here than the decision process behind them.
First determine what money is actually available. Then decide whether using part of it for the mortgage fits current priorities. Finally, verify that the payment was applied as intended.
That sequence keeps the focus on the household’s financial situation rather than on a payment trick.
Compare Realistic Scenarios Before Making a Change
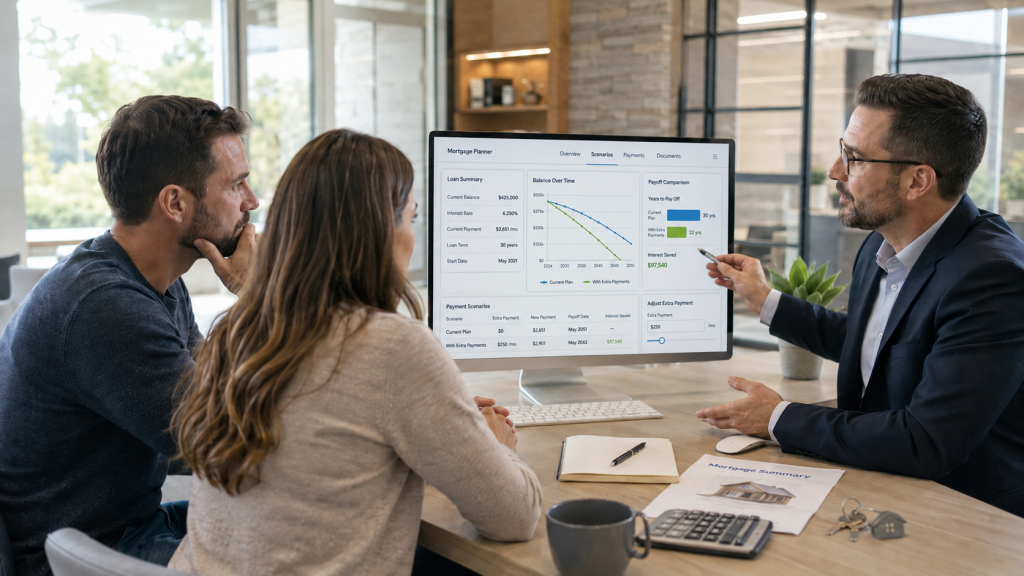
A useful way to reduce guesswork is to compare a few realistic scenarios based on the current mortgage.
The first scenario should usually be the existing payment schedule. That provides a baseline.
From there, a homeowner might compare what happens if a manageable additional amount is paid regularly, if occasional funds are directed toward principal, or if the payment changes after another obligation ends.
The purpose is not to identify one universal “best” method. It is to understand what each option requires from the household and what it could change about the mortgage.
Keep the assumptions realistic. A scenario that depends on income that is uncertain or ignores known expenses may produce an attractive result on paper without being practical in real life.
Homeowners should also avoid treating projections as promises. A projected payoff timeline depends on the information entered and assumes the planned payments continue. If income, expenses, or payment amounts change, the timeline can change too.
The value of comparing scenarios is clarity. It allows a homeowner to see the tradeoffs before committing additional cash.
Review the Plan and Adjust When Life Changes
A faster-payoff plan should not be set once and ignored.
Mortgage balances change, but so do household finances. Income can rise or fall. Expenses may increase. Another obligation may be paid off. A major repair, family change, or new savings goal may affect how much money can reasonably go toward the mortgage.
Review the plan periodically and compare it with the current situation.
Useful questions include:
- Is the principal balance moving as expected?
- Are additional payments being applied correctly?
- Is the payment amount still comfortable?
- Have recurring expenses changed?
- Are savings and reserves still adequate?
- Has another financial priority become more important?
Adjusting the plan does not mean it failed. A good strategy is flexible enough to respond to real financial conditions.
The goal is steady, informed progress rather than the shortest possible timeline at any cost.
Frequently Asked Questions
What should I check first if I want to pay off my mortgage faster?
Start with the current principal balance, interest rate, required monthly payment, remaining loan term, and recent mortgage statements. Then review household cash flow, savings, and other financial obligations so any additional payment is based on money that is realistically available.
Do I need to refinance to pay my mortgage off faster?
No. A homeowner can evaluate ways to pay an existing mortgage off sooner without replacing the loan. The appropriate approach depends on the current mortgage terms, household cash flow, and other financial priorities.
Should I use all of my extra cash for the mortgage?
Not necessarily. Emergency savings, home maintenance, insurance, taxes, healthcare, and other expenses may require accessible cash. The amount directed toward the mortgage should fit the broader household financial plan.
How often should I review a mortgage payoff plan?
There is no single schedule that fits every household. It is reasonable to revisit the plan when income, major expenses, savings needs, or other financial obligations change, and to periodically confirm that payments are being applied as expected.
Can paying extra principal reduce mortgage interest?
It can. Reducing the outstanding principal earlier may reduce the amount of interest paid over the remaining life of the loan, depending on the mortgage terms, timing of payments, and how the servicer applies the additional amount.
Build the Plan Before You Increase the Payment
Paying a mortgage off faster should begin with better information, not a random additional payment. Understand the current loan, decide what a faster payoff means for the household, review usable cash flow, protect necessary reserves, and compare realistic scenarios before making a change.
United Financial Freedom’s Mortgage Payoff Strategy resource provides the broader framework for organizing these decisions. Use it as the starting point for evaluating how an earlier payoff may fit your mortgage, cash flow, and longer-term financial priorities.
The objective is not to force the mortgage into the shortest possible timeline. It is to make each payment decision with a clearer understanding of what it changes and what the household can realistically sustain.