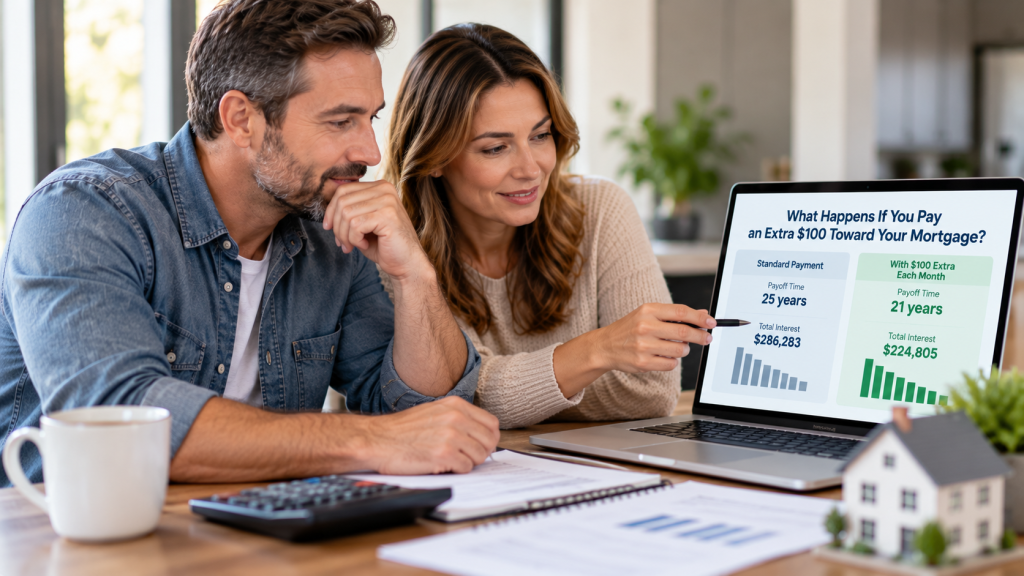
An extra $100 each month might seem small compared with your total mortgage balance. However, when that money is applied directly toward principal, it can affect more than the payment made that month.
Reducing the outstanding balance may change how much interest accrues during later payment periods. Over time, recurring principal reductions can also shorten the estimated repayment timeline.
But how much difference can an extra $100 mortgage payment actually make?
Paying an extra $100 toward your mortgage each month may reduce future interest and help you pay off the loan sooner, provided the additional funds are correctly applied to principal.
The effect depends on your current balance, interest rate, remaining loan term, and payment schedule.
An additional payment does not automatically produce the same benefit for every homeowner. Understanding the numbers behind your own mortgage is essential before deciding whether to increase your payments.
What Happens When You Add $100 to Your Mortgage Payment?
For a typical fixed-rate mortgage, each scheduled principal-and-interest payment covers interest and reduces the outstanding loan balance.
Adding $100 specifically toward principal can increase the amount by which that balance declines.
Your Principal Balance Decreases Faster
Suppose your scheduled mortgage payment includes $400 toward principal during a particular month.
If you make another $100 principal-only payment, the total principal reduction associated with those payments becomes $500.
The additional money reduces the balance beyond what the original repayment schedule required.
This matters because future interest is generally calculated using the outstanding balance rather than the original amount borrowed.
The earlier the additional principal is credited, the sooner later calculations may reflect that reduction.
Future Interest May Be Lower
For many traditional mortgages, a smaller outstanding principal balance results in less interest accruing during subsequent periods.
Consider a simplified example involving a 6% annual interest rate.
An additional $100 principal reduction would lower one subsequent month’s interest by approximately $0.50 under a standard monthly interest calculation.
That initial difference may appear modest.
However, the lower interest amount can allow slightly more of a later scheduled payment to reduce principal.
Repeated additional payments can strengthen this effect over time.
The actual outcome depends on the loan’s interest calculation method and payment processing.
Your Required Payment Usually Stays the Same
Paying an additional $100 generally does not automatically reduce the required monthly principal-and-interest installment on a typical fixed-rate mortgage.
Instead, a larger portion of subsequent scheduled payments may reduce principal.
The result can be a shorter projected repayment period.
Homeowners should still confirm their mortgage terms because different loan structures may operate differently.
How Much Difference Could an Extra $100 Make?
A hypothetical mortgage example can help illustrate the potential effect of consistent additional principal payments.
Consider a homeowner who has 25 years remaining on a fixed-rate mortgage and wants to explore whether another $100 per month could affect the payoff timeline.
Starting Mortgage Details
| Mortgage information | Hypothetical amount |
| Outstanding principal | $220,000 |
| Fixed annual interest rate | 6% |
| Remaining term | 25 years |
| Required monthly principal-and-interest payment | $1,417.46 |
| Additional monthly principal | $100 |
| Total planned monthly payment | $1,517.46 |
The figures assume a traditional fixed-rate mortgage using standard monthly amortization.
Property taxes, insurance, penalties, and other expenses are excluded.
Scenario 1: Continue Scheduled Payments
If the homeowner continues paying approximately $1,417.46 in principal and interest each month, the loan is scheduled for repayment over 300 months.
Using the stated assumptions, the projected remaining interest is approximately $205,239.
That represents interest expected from the calculation’s starting point through the remaining loan term.
It does not include interest already paid before the example begins.
Scenario 2: Add $100 Monthly
Now assume the homeowner contributes another $100 toward principal every month, beginning with the next scheduled payment.
The new total monthly contribution becomes approximately $1,517.46.
Under the same amortization assumptions, the mortgage would be projected to reach zero during the 259th payment month.
That represents approximately 41 fewer monthly payment periods.
Estimated remaining interest would decrease to approximately $172,666.
The difference between the two interest projections is approximately $32,573.
Comparing Both Repayment Scenarios
| Estimated result | Regular payments | Extra $100 monthly |
| Monthly principal and interest | $1,417.46 | $1,517.46 |
| Payments remaining | 300 | 259 |
| Remaining interest | $205,239 | $172,666 |
| Reduction in payment periods | — | 41 months |
| Estimated interest difference | — | $32,573 |
These figures are hypothetical, rounded calculations, not customer results or guaranteed savings.
They assume the fixed interest rate remains unchanged, additional funds are promptly credited toward principal, and the selected payments continue. The final installment may be smaller than the normal monthly amount.
Actual results depend on the mortgage agreement, interest-accrual conventions, and servicer procedures.
Why the Timing of Extra Payments Matters
An additional $100 payment does not have the same impact on every mortgage.
The remaining loan term and timing of the contribution influence how much future interest can be affected.
Starting Earlier Can Change More Payment Periods
Suppose two homeowners have similar mortgage interest rates but different remaining loan terms.
One has 25 years of payments remaining. The other has five years.
An extra $100 contributed by the first homeowner may influence interest calculations across more future periods.
The second homeowner has fewer remaining periods during which the reduced balance can affect interest.
This does not mean additional payments near the end of a mortgage have no value.
It means the calculation should reflect how much time remains.
Payment Consistency Affects the Projection
An early payoff estimate involving an extra $100 every month assumes those payments continue according to the modeled schedule.
If the homeowner skips several contributions or reduces the amount, the projected payoff date may change.
Voluntary extra payments should be distinguished from the required mortgage payment.
The household generally remains responsible for the scheduled installment even when additional principal payments are paused.
Verify When Funds Are Credited
Mortgage servicers may process additional payments according to different procedures.
Some permit homeowners to designate funds as principal-only.
Others may require specific instructions or process payments according to separate rules.
Before increasing payments, confirm how the additional amount will be credited.
Afterward, review mortgage statements to ensure the principal balance reflects the intended contribution.
Should You Pay $100 Every Month or Make Occasional Extra Payments?
A recurring additional payment is one way to reduce principal, but some homeowners prefer contributing larger amounts occasionally.
The approaches differ in timing, consistency, and financial flexibility.
The Predictability of Monthly Contributions
An additional $100 per month represents $1,200 over 12 months.
For a household with steady income and sufficient reserves, that may be a manageable recurring amount.
Consistent contributions can also make repayment projections easier to follow.
However, money applied toward principal generally becomes less accessible for other household needs.
The additional amount should therefore reflect the family’s actual financial circumstances.
Occasional Contributions May Offer Flexibility
Some homeowners may prefer retaining available funds until anticipated expenses have been covered.
An occasional principal payment could then be considered when sufficient money remains.
For example, someone might contribute $300 after completing several months of planned savings contributions.
A later lump-sum payment and several earlier monthly payments may have different effects, even when the total amount contributed is identical.
The timing and outstanding principal balance influence the outcome.
Consider Your Financial Priorities
There is no universal rule requiring homeowners to contribute every available dollar toward their mortgage.
Emergency savings, insurance, home maintenance, retirement contributions, and other obligations may affect the decision.
Reducing principal can lower borrowing costs, but it also commits money to home equity.
Home equity is not equivalent to cash readily available in a savings account.
A financially sustainable approach should account for both repayment goals and accessible savings.
How to Estimate What an Extra $100 Could Do for Your Mortgage
The hypothetical example illustrates one possible outcome, but your mortgage may have a different balance, interest rate, or remaining repayment period.
A calculation using your actual loan information can provide a more relevant estimate.
Begin with your latest mortgage statement.
Identify the current outstanding principal, contractual interest rate, required principal-and-interest payment, and remaining term.
Then compare the scheduled repayment timeline with one that includes an additional $100 toward principal each month.
The difference may help you estimate how the payment could affect your remaining loan term and interest.
For broader guidance, United Financial Freedom explains how mortgage payoff strategies can be evaluated alongside household cash flow.
Understand the Calculation’s Assumptions
A standard calculation may not fully account for adjustable interest rates, interest-only periods, unusual payment arrangements, or prepayment restrictions.
It may also assume that all additional payments are made consistently and credited immediately.
Projected results should be treated as estimates rather than promises.
Before making changes, confirm the relevant provisions with your mortgage servicer.
Compare the Commitment With the Possible Benefit
An additional $100 monthly contribution represents money that could otherwise remain available for savings or other financial priorities.
The potential interest difference should therefore be evaluated alongside the additional funds contributed and the household’s need for flexibility.
A shorter estimated payoff date is useful information, but it should not be the only reason for changing payments.
Is an Extra $100 Mortgage Payment Right for Your Situation?
Adding $100 toward principal may shorten the repayment period on many traditional mortgages.
However, the appropriate additional amount depends on your loan and financial circumstances.
Before making changes, review your current mortgage information, confirm how extra payments are applied, and consider whether the commitment is sustainable.
United Financial Freedom provides educational information about mortgage payoff planning and the factors that influence earlier repayment.
Interested in Exploring Your Mortgage Payoff Options?
Understanding your outstanding balance, interest rate, and available cash flow can help you evaluate how additional payments may affect your mortgage.
Explore Mortgage Payoff Options With United Financial Freedom
Frequently Asked Questions
Does paying an extra $100 on my mortgage automatically reduce interest?
Not automatically. An additional $100 may reduce future interest when correctly applied toward principal, but the effect depends on the outstanding balance, loan terms, and payment timing.
How much faster could I pay off my mortgage with an extra $100 monthly?
The difference depends on your mortgage balance, interest rate, and remaining term. A loan-specific calculation can estimate how many payment periods may be removed from the original schedule.
Will an extra $100 reduce my required monthly mortgage payment?
Usually not. On a typical fixed-rate mortgage, additional principal payments reduce the outstanding balance without automatically changing the required monthly principal-and-interest installment.
Can I stop making additional $100 payments later?
Voluntary additional principal payments can often be reduced or stopped while required mortgage payments continue. However, homeowners should review their loan terms and any separate repayment agreements.
Is paying an extra $100 better than keeping it in savings?
Not necessarily. The decision depends on emergency reserves, other financial obligations, mortgage borrowing costs, and household priorities. Accessible savings may be important for unexpected expenses.