Paying off a mortgage sooner can be a worthwhile financial goal, but a shorter repayment timeline does not automatically mean a homeowner has chosen the right approach.
Some mortgage acceleration mistakes begin with incorrect payment instructions. Others happen when homeowners rely on optimistic payoff projections, overlook household expenses, or misunderstand the terms of a financial program.
These problems can affect more than the expected payoff date. They may also reduce financial flexibility or create additional costs that were not considered when the plan began.
The most important mortgage acceleration mistakes to avoid involve inaccurate loan information, misapplied payments, unrealistic cash-flow assumptions, and repayment decisions that ignore other financial obligations.
Homeowners do not need to predict every future expense to create a responsible plan. However, they should understand what the strategy requires, how progress will be measured, and what circumstances may require an adjustment.
Recognizing these warning signs can help homeowners make better decisions before committing additional money to their mortgage.
Mistake 1: Using Incorrect Mortgage Information
One of the easiest ways to develop an unreliable repayment plan is to begin with outdated or incomplete loan information.
Homeowners sometimes rely on the original mortgage amount, the initial loan term, or an estimate of their remaining balance.
Those figures may no longer describe the mortgage accurately.
Confusing the Original Loan Amount With the Current Balance
The original principal is the amount borrowed when the mortgage began.
The current principal balance reflects the remaining amount after payments and other applicable adjustments.
A repayment projection based on the original loan amount may be misleading if the homeowner has already made several years of payments.
Even a relatively small difference between the assumed and actual balance can affect estimated interest and payoff calculations.
Homeowners should use a recent mortgage statement or other current information from their servicer.
Including Taxes and Insurance in Principal-and-Interest Calculations
Many homeowners make one monthly payment that includes principal, interest, property taxes, and homeowners insurance.
However, the amount applied toward the loan is not necessarily the same as the total amount withdrawn from the bank account.
Taxes and insurance generally do not reduce mortgage principal.
Using the entire monthly payment in an amortization calculation can therefore produce an incorrect projected payoff date.
Before comparing repayment scenarios, separate the principal-and-interest amount from escrow-related charges.
Overlooking the Remaining Loan Term
A homeowner who purchased a house three years ago does not have the same repayment starting point as someone beginning a new 30-year mortgage.
The remaining term matters because the loan has already progressed through part of its original schedule.
Accurate starting information helps homeowners avoid comparing their situation with examples that use different assumptions.
For broader guidance on reviewing an existing mortgage, see how to pay off a mortgage faster.
Mistake 2: Assuming Additional Payments Are Applied Correctly
Sending extra money to a mortgage servicer does not necessarily guarantee that it will be applied the way the homeowner expects.
An additional payment intended to reduce principal must be processed according to the loan agreement and the servicer’s procedures.
Failing to Specify a Principal-Only Payment
Some payment systems allow homeowners to identify additional funds specifically for principal.
Other systems may require different instructions.
Without confirming the procedure, a homeowner may assume that every additional dollar immediately reduces the outstanding balance.
Depending on the servicer and payment circumstances, funds may instead be credited toward future payments or handled under another permitted process.
The safest approach is to confirm payment instructions before sending additional funds.
Homeowners should then review their statements to verify that the principal balance reflects the intended payment.
Confusing an Advance Payment With Principal Reduction
A payment that advances the next due date is not necessarily equivalent to an extra principal-only payment.
The financial effect depends on how the transaction is credited.
For example, a homeowner who sends extra money intending to reduce principal should not assume that a statement showing a later payment due date confirms the intended result.
The updated principal balance and transaction details provide more useful information.
Ignoring Payment Processing Delays
Payment timing can also matter.
A homeowner may submit funds on a particular date, but the servicer may credit them according to the loan agreement and applicable processing rules.
For an approach that depends on specific timing assumptions, these details deserve attention.
A practical safeguard is to keep payment confirmations and review statements after additional payments are made.
This helps identify discrepancies before they affect several months of repayment planning.
Mistake 3: Committing More Cash Than the Household Can Sustain
Another mortgage acceleration mistake occurs when homeowners focus on the earliest possible payoff date without considering how much cash they need to keep available.
An aggressive repayment amount may produce an appealing projection while creating unnecessary financial pressure.
Treating Every Extra Dollar as Available for the Mortgage
Money remaining after ordinary monthly bills is not always disposable income.
Households face expenses that may occur quarterly, annually, or unexpectedly.
Property maintenance, insurance changes, vehicle repairs, medical expenses, and other obligations can affect the amount genuinely available for additional mortgage payments.
A homeowner who directs every apparent surplus dollar toward principal may later struggle to cover a necessary expense.
That risk should be considered before establishing a recurring additional payment.
Reducing Emergency Savings Too Far
Additional principal payments generally increase home equity.
However, home equity is not the same as money readily available in a savings account.
Accessing equity later may require selling the property or obtaining another financial arrangement, potentially involving approval requirements, fees, and borrowing costs.
Emergency reserves provide flexibility that an accelerated mortgage payoff does not automatically replace.
Homeowners should consider whether they have sufficient accessible savings before committing additional cash.
Making a Repayment Commitment That Cannot Adjust
A homeowner may be able to afford a larger payment during a period of stable income.
That does not guarantee the same amount will remain available indefinitely.
Changes in employment, household expenses, or personal circumstances may require different priorities.
A repayment approach should allow the homeowner to understand which payments are contractually required and which are voluntary.
If a strategy involves additional agreements, the obligations and conditions for changing or ending the arrangement should be reviewed in advance.
Mistake 4: Trusting Payoff Projections Without Checking the Assumptions
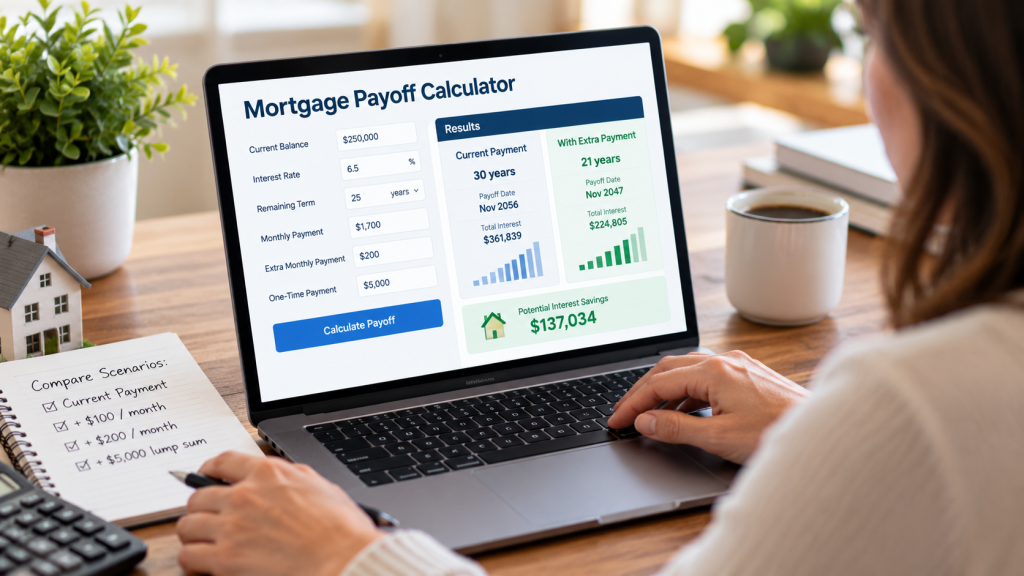
Mortgage payoff calculators and planning tools can help illustrate possible outcomes.
However, a projected payoff date is only as useful as the information and assumptions behind it.
Treating an Estimate as a Promise
A calculator may display an earlier payoff date based on continued additional payments.
That projection generally assumes the homeowner follows the entered repayment schedule.
If additional payments decrease, stop, or occur later than expected, the projected result may change.
Likewise, different loan structures or interest-calculation rules may affect the calculation.
A projected date should be understood as a scenario rather than a guarantee.
Ignoring Costs Outside the Mortgage Calculation
Some structured mortgage acceleration arrangements may involve program expenses, account fees, or separate borrowing costs.
A projection showing reduced mortgage interest does not necessarily include every expense associated with the approach.
Homeowners should understand what costs are included, which costs are excluded, and whether additional financial products are involved.
For example, a strategy that lowers projected mortgage interest but creates another interest expense requires evaluation of both amounts.
The relevant question is whether the overall financial arrangement makes sense, not simply whether one number looks favorable.
Comparing Results Based on Different Starting Conditions
Two repayment scenarios should use consistent starting information whenever possible.
Comparing one calculation based on the current principal balance with another based on the original loan amount can create misleading differences.
Similarly, assumptions about payment dates, interest rates, and fees should be clearly understood.
A reliable comparison identifies which variables are changing and which remain constant.
Homeowners exploring different repayment arrangements can review mortgage payoff strategies for a broader understanding of the planning considerations.
Mistake 5: Neglecting Regular Reviews and Financial Priorities
A mortgage acceleration approach should not be treated as a decision that never needs revisiting.
Even when the initial calculations are reasonable, changing household circumstances may affect whether the arrangement continues to make sense.
Failing to Review Progress
Homeowners may continue making additional payments without checking whether the outstanding principal is declining as expected.
Periodic reviews provide an opportunity to identify payment-processing problems, incorrect assumptions, or changes in available cash flow.
A useful review compares the current mortgage balance with the most recent projection and checks whether the payment arrangement remains affordable.
If the actual results differ, the homeowner should investigate the reason before relying on an updated payoff estimate.
Overlooking Other Financial Obligations
Mortgage repayment competes with other uses for household money.
A homeowner may have retirement savings goals, necessary home improvements, other debts, or upcoming education expenses.
Directing additional funds toward principal may be reasonable in some circumstances, but it is not automatically the best decision for every household.
Interest rates, liquidity needs, financial goals, and personal circumstances all influence the choice.
The purpose of a repayment review is to identify whether the mortgage plan still fits the broader financial picture.
Choosing a Program Without Understanding Its Terms
Homeowners should understand any mortgage acceleration program before agreeing to participate.
Important details include applicable fees, payment requirements, account arrangements, and what happens if the homeowner’s circumstances change.
Product information should be distinguished from general explanations of mortgage amortization.
The fact that a repayment strategy is described as structured or personalized does not establish a guaranteed financial advantage.
A homeowner should understand the actual arrangement rather than relying solely on projected results or promotional language.
Make Mortgage Repayment Decisions With Better Information
Avoiding mortgage acceleration mistakes begins with accurate information, realistic expectations, and an understanding of the financial commitments involved.
Before changing a repayment approach, homeowners can review their mortgage statements, confirm payment instructions, and consider how additional payments fit their household finances.
United Financial Freedom provides information about mortgage repayment strategies and helps homeowners explore the factors involved in evaluating an earlier payoff.
Interested in Reviewing Your Mortgage Payoff Options?
Understanding your existing mortgage and available cash flow can help you evaluate possible repayment approaches without relying on generalized payoff promises.
Explore Mortgage Payoff Options With United Financial Freedom
Frequently Asked Questions
What is the most common mistake when trying to accelerate a mortgage?
A common mistake is choosing an additional payment amount without considering the full household budget. Homeowners should also verify that payments are credited toward principal and that payoff calculations use accurate loan information.
Can an incorrect extra payment delay my mortgage payoff plan?
It can affect the intended repayment outcome. If additional funds are not applied toward principal as expected, the projected balance and payoff date may differ from the original calculation. Homeowners should review payment confirmations and mortgage statements.
Should I stop mortgage acceleration if my income changes?
Not necessarily, but the repayment approach may need to be reassessed. Homeowners should review required payments, available reserves, and other obligations before deciding whether voluntary additional payments remain affordable.
Are mortgage acceleration programs guaranteed to reduce interest costs?
No. Results depend on the loan terms, repayment behavior, payment timing, and any associated costs. Program projections should be reviewed carefully, and homeowners should not assume that advertised outcomes will apply to every mortgage.
How often should I review an accelerated mortgage payoff plan?
There is no single required review schedule for every homeowner. Checking mortgage statements regularly and reassessing the plan after significant income or expense changes can help ensure the repayment approach remains accurate and financially practical.