Yes. On many standard amortizing mortgages, an additional payment that is properly applied to principal can reduce future mortgage interest because it lowers the balance on which interest is calculated.
The basic mechanism is straightforward. A mortgage charges interest on the outstanding principal balance. When that balance falls sooner than the original repayment schedule expected, future interest is calculated on less debt. If regular scheduled payments continue, the mortgage may also reach a zero balance earlier than originally planned.
But the size of the benefit depends on the actual loan. The amount of extra principal, when it is paid, the mortgage rate, the remaining term, and the way the servicer applies the payment all matter.
That is why the useful question is not simply whether paying extra principal works. It is how much a particular payment changes the balance, future interest, payoff timing, and household cash flow.
Why Extra Principal Can Reduce Future Mortgage Interest
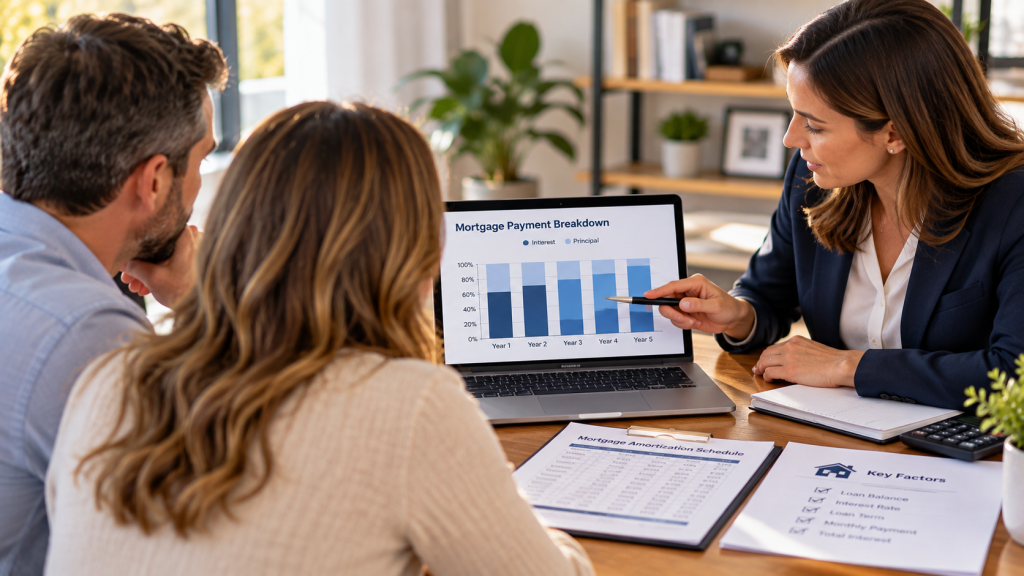
A standard amortizing mortgage is built around a declining principal balance. Each scheduled payment covers the interest due for that period and reduces some principal.
If a homeowner follows only the original payment schedule, the balance declines according to that schedule. An additional principal payment changes the starting point for future calculations.
Suppose a mortgage balance is $250,000. If a homeowner makes an extra $5,000 payment and the servicer applies the full amount to principal, the balance is reduced to $245,000 before later scheduled payments continue.
The interest rate has not changed. The mortgage term in the contract has not necessarily changed either. What changed is the amount of debt still outstanding.
Because later interest is calculated using a smaller balance, the homeowner may pay less interest over the remaining life of the loan.
This is the same reason principal reduction matters throughout an amortization schedule: less outstanding debt generally means less future interest at the same rate.
For a broader explanation of how balance, rate, term, and repayment activity affect mortgage interest, see How to Reduce Mortgage Interest.
Why Timing and Payment Pattern Matter
The same additional principal payment can have a different effect depending on when it is made.
An extra payment made earlier in the mortgage usually has more remaining payment periods during which the lower balance can affect future interest. The same payment made near the end of the loan has less time to influence the remaining interest because fewer scheduled payments remain.
That does not mean every homeowner should immediately send extra cash to the mortgage. It simply means timing is one of the variables that determines the result.
The mortgage rate also matters. At a higher rate, the same amount of principal produces a larger interest charge than it would at a lower rate. Reducing that balance sooner can therefore have a different dollar effect depending on the rate.
Remaining term matters for the same reason. A loan with 20 years left has more future payment periods than one with three years remaining.
Extra principal can also be paid in different ways.
Some homeowners add a fixed amount to every monthly payment. Others make occasional lump-sum payments when they have available cash from a bonus, tax refund, or another source.
Both approaches can reduce principal when the funds are applied correctly, but they do not always produce the same result.
A recurring monthly amount lowers the balance in smaller steps throughout the year. A lump sum lowers the balance at the time it is made.
Timing matters because a balance reduced earlier remains lower for more future payment periods.
That means two strategies involving the same total extra dollars may produce different interest savings if the money reaches principal at different times.
A useful comparison therefore looks at the current principal balance, proposed extra payment, interest rate, and remaining term together rather than relying on a rule such as “one extra payment a year will always save a certain amount.
Extra Principal Can Change Both Interest and Payoff Timing
Extra principal can affect more than the interest total.
If a homeowner continues making the regular required payment after reducing principal, the balance may reach zero before the original maturity date. That can shorten the payoff timeline as well as reduce the amount of interest paid.
These two effects are related but should still be evaluated separately.
One homeowner may care most about lowering total interest. Another may care about reaching a mortgage-free date sooner. A third may value flexibility and prefer to make occasional additional payments rather than commit to a higher amount every month.
The mortgage numbers can show what each approach changes.
A useful comparison should include:
- projected remaining interest,
- estimated payoff date,
- additional cash required,
- and the effect on monthly or annual household cash flow.
This prevents an extra-payment strategy from being judged only by the size of the balance reduction.
Homeowners who want to compare different payoff approaches can review Mortgage Payoff Strategies Compared for additional context on how timing and repayment patterns can change the mortgage timeline.
How to Make Sure Extra Money Actually Reduces Principal
An extra payment only produces the intended principal reduction if the loan servicer applies the money correctly.
Servicers may provide a specific option for additional principal, principal-only payments, or another designated payment type. Homeowners should follow the servicer’s instructions rather than assume that every amount sent above the scheduled payment will automatically be treated the same way.
If extra funds are instead treated as an advance toward a future monthly payment, the effect may be different from an immediate principal reduction.
After an extra payment is processed, the mortgage statement or online account can be checked to confirm that the principal balance declined by the expected amount.
It is also worth reviewing the loan agreement for any applicable prepayment terms. Mortgage terms vary, so homeowners should check the rules that apply to their own loan instead of relying on a general assumption.
This verification step is simple but important. The strategy depends on reducing principal sooner. If the payment is not applied to principal as intended, the expected interest and payoff effects may not occur.
The payment amount also needs to be viewed in context.
Making a large additional payment and then having to borrow money at a higher interest rate to cover an emergency could create a different financial problem.
The mortgage is one part of the household’s finances, not the only one.
When Paying Extra Principal May Not Be the First Priority
The fact that extra principal can reduce mortgage interest does not mean it should automatically receive every available dollar.
Money sent to principal becomes home equity. It is no longer immediately available in a checking or savings account.
That tradeoff matters if the household also needs cash for emergencies, home repairs, insurance costs, medical expenses, retirement contributions, or other debts.
Higher-interest debt can also change the decision. A household carrying a large credit card balance may have a very different set of priorities from one with no other debt and a substantial emergency reserve.
Before making an extra principal payment, homeowners may want to review:
- emergency savings,
- other debt balances and rates,
- near-term household expenses,
- income stability,
- and the amount of cash that would remain available afterward.
The purpose is not to argue against extra principal. It is to make sure the mortgage is evaluated as one part of the household’s finances.
A payment that reduces future mortgage interest can still create pressure elsewhere if it leaves too little accessible cash.
Homeowners considering faster repayment can also review What to Calculate Before Paying Off a Mortgage Early for a closer look at the figures that matter before committing additional cash.
How to Evaluate an Extra Principal Payment
A useful decision starts with the mortgage as it exists today.
Gather the current principal balance, interest rate, remaining term, required principal-and-interest payment, and the amount and timing of the proposed extra payment.
Then compare the existing repayment path with the proposed one.
Look at:
- estimated remaining interest,
- projected payoff date,
- total additional cash committed,
- and the amount of liquid savings that would remain.
The result will not be the same for every homeowner.
A recurring additional payment may produce a meaningful change in one mortgage and a modest change in another. A lump sum may be more practical for one household, while another may prefer to keep additional cash available.
The important point is to measure the effect rather than assume it.
Paying extra principal does not lower the fixed mortgage rate. It works by lowering the balance sooner. Once that balance is lower, future interest is calculated on less outstanding debt.
That is the mechanism behind the potential savings, and it is the number homeowners should verify when deciding whether an extra payment fits their repayment plan.
Frequently Asked Questions
Does paying extra principal lower the mortgage interest rate?
No. Extra principal does not change the interest rate on a fixed-rate mortgage. It lowers the outstanding balance. Because future interest is calculated using that smaller balance, the total amount of interest paid over time may decrease.
Is it better to make extra principal payments early in the mortgage?
Earlier principal reductions generally have more remaining payment periods during which the lower balance can affect future interest. Whether making an early extra payment is appropriate still depends on the mortgage terms, available cash, other debts, and household priorities.
Should an extra mortgage payment be marked as principal only?
Homeowners should follow their loan servicer’s instructions for making additional principal payments. The goal is to ensure the extra amount is applied directly to principal rather than treated as an advance toward a future scheduled payment.
Can extra principal payments shorten the mortgage term?
They can. If principal is reduced faster while the regular scheduled payment continues, the mortgage may reach a zero balance before the original maturity date. The exact change depends on the amount and timing of the extra payments, the interest rate, and the remaining term.
Is a lump-sum payment better than paying a little extra each month?
Neither approach is universally better. Both can reduce principal when applied correctly. The outcome depends on how much is paid, when it reaches principal, the mortgage rate, and how long the loan would otherwise remain outstanding.