A mortgage payoff calculator can help you estimate when your home loan may be paid off and how additional principal payments could change that timeline. However, the results are only as useful as the information you enter.
For example, using the original mortgage amount instead of your current balance can produce an inaccurate estimate. Including property taxes and insurance in a principal-and-interest calculation may also affect the results.
Learning how to use a mortgage payoff calculator involves five steps: gathering your mortgage information, entering the correct figures, calculating your current payoff schedule, testing extra payments, and reviewing the results.
This process helps you understand how different payment amounts may influence your loan without immediately changing your repayment plan.
Whether you recently purchased a home or have been making payments for several years, using accurate mortgage information can provide a clearer picture of your remaining financial commitment.
Step 1: Gather Your Current Mortgage Information
Before using a mortgage payoff calculator, locate your latest mortgage statement.
Your original loan documents may contain useful information, but your current statement provides a more accurate starting point for estimating the remaining repayment period.
Find Your Outstanding Principal Balance
The principal balance represents the remaining amount borrowed that has not yet been repaid.
This differs from the original mortgage amount.
Suppose you originally borrowed $275,000. After several years of regular payments, your principal balance may be lower.
Entering $275,000 instead of the actual remaining balance would cause the calculation to start with an incorrect amount.
Look for the outstanding principal balance on your mortgage statement.
Do not confuse it with your home’s estimated market value or available equity. Those figures measure different things.
Confirm Your Interest Rate
Your mortgage interest rate affects how much interest is calculated on the outstanding balance.
For a fixed-rate mortgage, the contractual interest rate generally remains unchanged throughout the repayment term.
If you have an adjustable-rate mortgage, future interest changes may affect the accuracy of a fixed-rate calculation.
Use the interest rate that currently applies to your loan rather than an advertised rate for new mortgages.
Determine the Remaining Term
The remaining mortgage term represents the time left under the existing repayment schedule.
For example, if you began a 30-year mortgage five years ago and followed the scheduled payments, approximately 25 years may remain.
Some calculators request years remaining, while others use months.
Twenty-five years represents approximately 300 scheduled monthly payments.
Using the correct remaining term is essential because the calculator estimates repayment from your current position, not necessarily from the original loan date.
Separate Principal and Interest From Escrow
Your mortgage statement may include property taxes and homeowners insurance within the total monthly payment.
These amounts generally do not reduce the outstanding loan principal.
If your monthly payment is $1,800 but $350 covers taxes and insurance, the principal-and-interest portion would be $1,450.
A standard mortgage payoff calculation generally uses the principal-and-interest amount.
Separating these figures helps avoid treating escrow expenses as loan repayment.
Step 2: Enter the Correct Numbers Into the Calculator
Once you have gathered your mortgage information, enter it into the appropriate calculator fields.
The exact layout may differ between tools, but most mortgage payoff calculations rely on similar information.
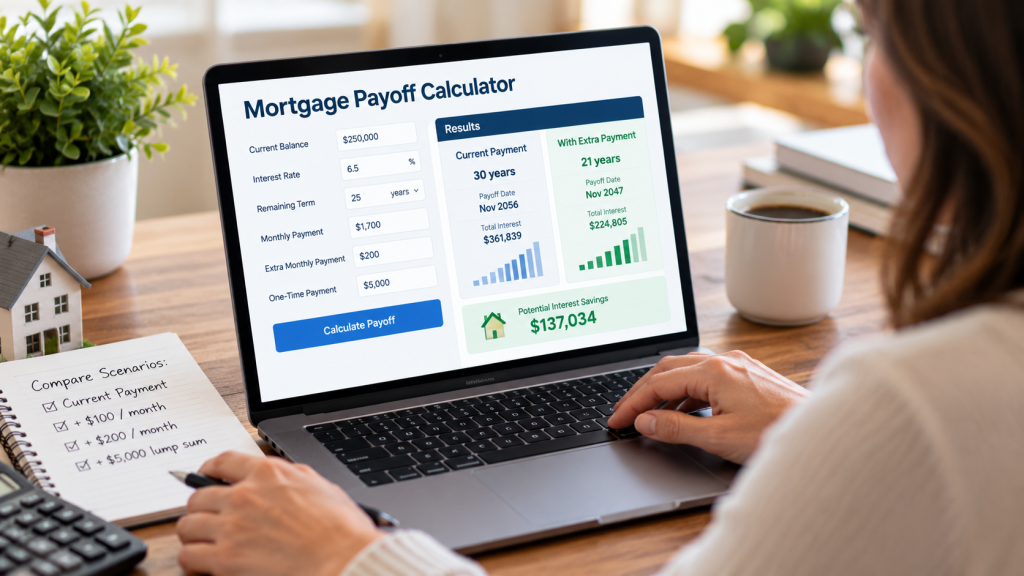
Understand the Main Calculator Fields
| Calculator Field | Information to Enter |
| Current Mortgage Balance | Outstanding principal |
| Annual Interest Rate | Current contractual rate |
| Remaining Loan Term | Years or months remaining |
| Monthly Mortgage Payment | Principal-and-interest amount |
| Extra Monthly Payment | Additional principal amount |
| One-Time Extra Payment | Optional lump-sum principal payment |
Some calculators determine the regular monthly principal-and-interest payment automatically.
Others require you to enter the scheduled payment directly.
If the calculated payment differs substantially from your mortgage statement, review the inputs before proceeding.
The difference could result from an incorrect term, an inappropriate interest-rate assumption, or a loan structure that the calculator does not fully support.
Begin Without Extra Payments
When learning how to use a mortgage payoff calculator, begin with your current repayment schedule.
Enter zero in the additional payment field.
This establishes a baseline showing how the mortgage may be repaid if you continue making the required payments under the stated assumptions.
For example, a homeowner with 20 years remaining should generally expect the baseline payoff projection to be consistent with that remaining period.
Once you have the baseline, you can evaluate alternative payment scenarios.
Double-Check Your Entries
Before reviewing the results, confirm that each number is correct.
Check whether the interest rate field expects a percentage or decimal, and whether the term is measured in months or years.
Also confirm that additional payment amounts are not accidentally included in the regular payment field.
Correcting these mistakes before calculating can prevent misleading estimates.
Step 3: Understand Your Current Mortgage Payoff Estimate
After entering the baseline information, review the projected payoff results.
A calculator may display the remaining number of payments, estimated payoff date, and interest expected over the rest of the mortgage.
These figures describe a projected repayment schedule rather than a guaranteed financial outcome.
Review the Estimated Payoff Date
The estimated payoff date represents when the remaining principal balance may reach zero if payments follow the assumptions used in the calculation.
For a typical fixed-rate mortgage, the baseline estimate should generally align with the remaining loan term.
If the result differs significantly from your expected maturity date, review the entered balance, interest rate, and required payment.
An online calculation is also different from an official mortgage payoff statement.
A lender-issued payoff quote may include accrued interest and other applicable charges through a specified date.
Understand Remaining Interest
Remaining interest represents the estimated borrowing cost over the rest of the repayment period.
This amount differs from interest already paid during earlier years.
It is also different from the mortgage’s stated annual interest rate.
For example, a 5% mortgage interest rate does not mean the total remaining interest cost equals 5% of the current principal balance.
The remaining interest depends on how long the balance stays outstanding and how payments reduce it.
Record the Starting Figures
Before changing any inputs, record the baseline payoff date, estimated remaining interest, and number of payments.
These values provide a reference for comparing alternatives.
Without this starting point, it can be difficult to determine what changed after an additional payment amount was entered.
A useful mortgage payoff strategy begins with understanding the existing loan before evaluating repayment adjustments.
Step 4: Test Different Additional Principal Payments
After establishing your baseline, you can examine how additional principal payments may affect the projected payoff schedule.
The purpose is to compare scenarios, not to assume that every homeowner should make the largest possible extra payment.
Change One Variable at a Time
Consider a hypothetical mortgage with these starting details:
- Outstanding principal: $180,000
- Fixed annual interest rate: 5%
- Remaining repayment term: 20 years
- Additional monthly principal payment: $0
First, calculate the current repayment schedule.
Next, keep the balance, interest rate, and remaining term unchanged while entering an additional $75 monthly principal payment.
This allows you to examine the effect of that particular change.
If you adjust several inputs simultaneously, identifying the cause of the difference becomes more difficult.
Compare the Revised Results
Review the alternative payoff date and estimated remaining interest.
Compare them with the baseline.
If the calculator assumes an additional $75 every month, the projection generally depends on those payments continuing.
A different payment amount or schedule could produce another result.
Similarly, a skipped payment or processing difference may affect the actual payoff timeline.
The estimated interest difference represents a comparison of borrowing costs, not cash immediately received by the homeowner.
Consider One-Time Principal Payments
Some calculators also allow users to examine a one-time extra principal payment.
For example, a homeowner might evaluate the possible effect of contributing an additional lump sum at a particular point in the repayment schedule.
The result depends on both the amount and when it is applied.
A one-time payment should not automatically be considered equivalent to recurring monthly contributions.
Homeowners should also evaluate whether those funds are needed for savings, property expenses, or other financial obligations.
Step 5: Review the Calculation Before Changing Payments
A calculator can help you understand potential repayment changes, but it cannot determine whether a particular payment amount fits your household finances.
Before making actual changes, review the mortgage agreement and the financial commitments involved.
Confirm How Your Servicer Applies Extra Payments
Some mortgage servicers allow homeowners to designate additional payments as principal-only.
Others may use different payment procedures.
Before contributing extra funds, confirm how the payment will be processed.
A payment credited toward future scheduled installments is not necessarily equivalent to an additional principal reduction.
After making a payment, review your statement to confirm that the outstanding balance changed as expected.
Account for Household Expenses
Additional mortgage payments should be evaluated alongside emergency savings, regular bills, insurance, maintenance, and other financial responsibilities.
Money used to reduce mortgage principal generally becomes part of home equity.
Home equity is not the same as money readily available in a savings account.
A shorter projected repayment period may be appealing, but committing too much cash toward principal can reduce financial flexibility.
Understand the Calculator’s Limitations
A standard mortgage payoff calculation may not fully account for adjustable interest rates, special loan terms, fees, or different payment-processing rules.
Results can also change if income or household expenses affect the ability to maintain additional payments.
For that reason, payoff dates and interest differences should be treated as estimates.
Homeowners interested in broader repayment planning can explore how to pay off a mortgage faster and the financial considerations involved.
Use Your Results to Explore Mortgage Payoff Options
Learning how to use a mortgage payoff calculator gives you a clearer way to evaluate possible repayment changes.
Start with your current mortgage information, calculate the existing schedule, and compare realistic alternatives.
The goal is to understand what different payment assumptions mean for your mortgage while considering other financial priorities.
United Financial Freedom provides educational information about mortgage payoff planning and the factors that can influence an earlier repayment timeline.
Interested in Exploring Your Mortgage Payoff Options?
Understanding your outstanding balance, interest rate, and available cash flow can help you evaluate repayment possibilities based on your own circumstances.
Explore Mortgage Payoff Options With United Financial Freedom
Frequently Asked Questions
Should I use my original mortgage balance or current balance?
Use your current outstanding principal balance when calculating the remaining mortgage payoff. The original loan amount does not reflect principal already repaid.
What if the calculator’s payment does not match my mortgage statement?
Confirm that you entered the correct balance, interest rate, remaining term, and principal-and-interest payment. Differences may also reflect loan features or calculation methods the tool does not support.
Can I use a mortgage payoff calculator with an adjustable-rate loan?
You can model a scenario using an assumed interest rate, but a basic fixed-rate calculator may not account for future rate adjustments. Treat the estimate cautiously.
Why should I calculate my current repayment schedule first?
The current schedule provides a baseline for comparison. Keeping the starting information consistent helps show the estimated effect of additional principal payments.
Does entering an extra payment mean my lender will apply it to principal?
No. A calculator models an assumed payment arrangement. You should confirm your mortgage servicer’s procedures and verify that actual additional payments are credited as intended.