A few years into a mortgage, many homeowners look at the balance and wonder why it has not fallen as much as they expected. They may have made dozens of on-time payments, yet a large portion of the original principal is still there.
That pattern is usually explained by amortization, not by a change in the mortgage rate. In a typical fixed-rate mortgage, the scheduled principal-and-interest payment can stay the same while the amount going toward interest and principal changes from month to month.
Early in the loan, the outstanding balance is at or near its highest point. Because interest is calculated using that larger balance, more of the payment generally goes toward interest. As principal declines, the interest portion usually becomes smaller and more of the scheduled payment can reduce principal.
Understanding that pattern makes the first years of a mortgage much easier to read.
Why Interest Takes a Larger Share Early in the Mortgage
Mortgage interest is tied to the amount still owed. At the beginning of the loan, very little principal has been paid down, so the outstanding balance is usually close to the original amount borrowed.
A larger balance produces a larger interest charge than a smaller balance at the same rate. That is why the interest portion tends to be heavier during the early years.
Suppose a homeowner has a fixed interest rate. The rate itself does not need to change for the interest portion of the payment to fall over time. What changes is the balance.
Each scheduled payment reduces principal by some amount. Once principal is lower, the next interest calculation is based on less outstanding debt. The process repeats as the mortgage moves through its repayment schedule.
This is also why saying that the lender “takes the interest first” can give the wrong impression. Principal and interest are both part of a standard amortizing mortgage payment from the beginning. The split changes because the balance changes.
For a broader look at the factors that influence mortgage interest, homeowners can review How to Reduce Mortgage Interest.
How Amortization Changes the Payment Month by Month
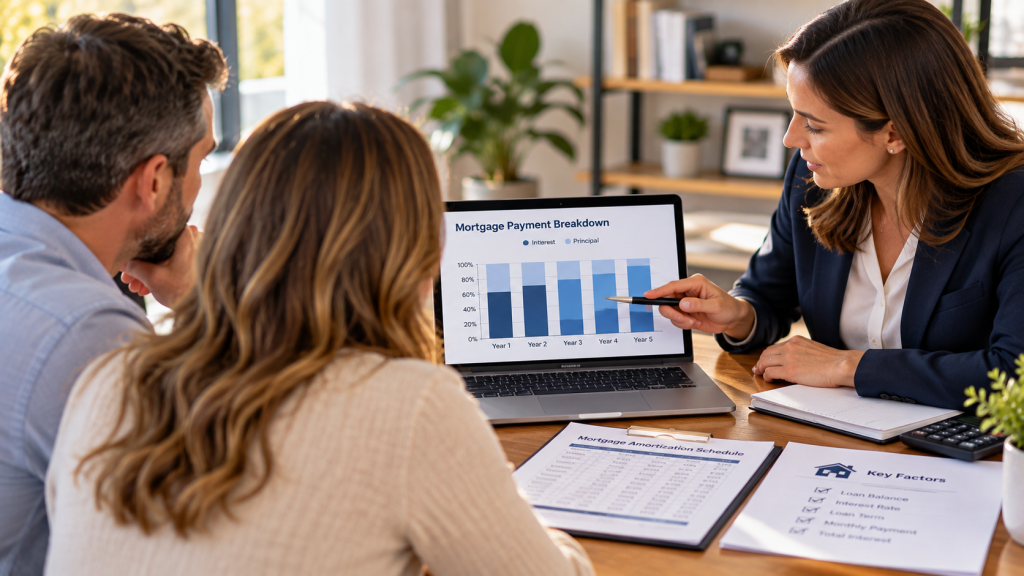
An amortization schedule lays out the planned repayment of the mortgage. It shows the scheduled payment, how much is applied to interest, how much reduces principal, and what balance remains afterward.
On a typical fixed-rate mortgage, the scheduled principal-and-interest payment stays level. What changes is the mix inside that payment.
Near the beginning, the balance is high, so the interest charge is also relatively high. After that interest is covered, the rest of the scheduled payment reduces principal.
Over time, principal reduction gradually lowers the balance. The next interest charge is then calculated on that smaller amount. More of the same scheduled payment can go toward principal.
This shift is gradual rather than sudden. There is no universal month in which every mortgage suddenly becomes “mostly principal.”
The exact pattern depends on the loan.
That is why an amortization schedule is more useful than a general rule about the first five or ten years. It shows what is scheduled to happen on the homeowner’s actual mortgage.
The early years can still feel slow because homeowners naturally compare the total amount they have paid with the amount by which the mortgage balance has fallen.
Those figures are not expected to match.
Only the principal portion of the payment reduces the loan balance. The interest portion covers the cost of borrowing the outstanding principal for that period.
If the monthly payment also includes escrow, the difference can look even larger. Property taxes and homeowners insurance collected through escrow do not reduce mortgage principal.
Looking at the mortgage statement helps separate those pieces instead of treating the entire amount leaving the household account as principal repayment.
Why There Is No Universal First-Year Interest Percentage
Homeowners sometimes ask what percentage of their payment goes toward interest during the first year, fifth year, or tenth year.
There is no single percentage that applies to every mortgage.
The answer depends on several loan characteristics, including:
- Original loan amount
- Interest rate
- Loan term
- Current principal balance
- Number of payments already made
A 15-year mortgage and a 30-year mortgage will not divide principal and interest in the same way.
Even two 30-year mortgages can have different principal-and-interest splits if their rates or balances are different.
That is why broad statements such as “most of your payment goes to interest for the first ten years” can be misleading. The exact timing depends on the mortgage.
The loan’s own amortization schedule provides the clearer answer because it shows how much interest is scheduled for each payment and how that amount changes as principal declines.
Homeowners can also compare the amortization schedule with their mortgage statements to see how actual payments are being applied.
Rate and Loan Term Shape the Early Interest Pattern
The interest rate influences how much interest is charged on the outstanding balance.
When other loan details are similar, a higher rate generally means more interest is due.
The repayment term also affects how quickly principal is scheduled to decline.
A 30-year mortgage spreads repayment across many more payments than a 15-year mortgage. This usually creates a lower required monthly principal-and-interest payment, but principal is also scheduled to decline more gradually.
A shorter mortgage generally requires a larger monthly payment because the principal has to be repaid across fewer years.
These differences explain why two homeowners can be at the same point in their mortgages and still see very different principal-and-interest splits.
The comparison should therefore include rate, term, and balance rather than asking only how many years have passed.
For homeowners who want to understand how different repayment structures can affect the mortgage timeline, Mortgage Payoff Strategies Compared provides additional context.
The main point here remains narrower: the amount of interest appearing in an early mortgage payment depends on the actual loan terms and outstanding balance, not on a universal schedule that applies to every homeowner.
What an Amortization Schedule Can Tell You
An amortization schedule gives homeowners a month-by-month view of the loan.
It can show:
- How much of an upcoming payment is scheduled for principal
- How much is scheduled for interest
- How the principal balance is expected to decline
- How the principal-and-interest split changes over time
- How many scheduled payments remain
This information helps explain why the balance behaves the way it does.
It also gives homeowners a baseline.
If someone is considering changing the repayment path, the current schedule shows what would happen if the mortgage continued as planned. Another scenario can then be compared against that baseline.
That does not mean the amortization schedule predicts every future event. Late payments, refinancing, loan modifications, additional principal payments, and other changes can alter the actual path.
But for a standard mortgage being paid according to schedule, it provides a useful view of how principal and interest are expected to change.
Homeowners considering an accelerated payoff can also review What to Calculate Before Paying Off a Mortgage Early for additional context on balance, remaining term, household cash flow, and projected interest.
The detailed question of how additional principal affects future interest belongs to a separate decision. The amortization schedule first establishes what the mortgage is expected to do under its current terms.
What the First Years of a Mortgage Actually Tell You
Seeing a large interest portion during the first years does not automatically mean something is wrong with the mortgage. It usually reflects the fact that the loan begins with its highest outstanding principal balance.
The useful step is to look at the actual numbers rather than rely on a general rule.
Check the current balance. Review the rate and remaining term. Look at the principal and interest amounts shown on the statement. Compare those figures with the amortization schedule.
That information can show whether the mortgage is progressing as expected and how the payment split is scheduled to change.
It can also prevent a homeowner from making a major repayment decision simply because the early interest amount feels high.
Whether additional principal should be paid is a separate question and depends on the homeowner’s financial situation, mortgage terms, and other priorities. The same is true of refinancing.
For this topic, the point is simpler: mortgage interest is typically heavier in the early years because the outstanding balance is larger.
As that balance declines, the interest portion generally declines with it.
Once homeowners understand that relationship, the first years of a mortgage become less mysterious. The monthly payment is no longer just one number leaving the bank account. It becomes a combination of principal reduction, interest cost, and, where applicable, separate escrow expenses.
Understanding that breakdown gives homeowners a clearer picture of what has already been paid, what remains, and how the mortgage is expected to change over time.
Frequently Asked Questions
Why does so much of a mortgage payment go toward interest at first?
At the beginning of a typical amortizing mortgage, the principal balance is relatively high. Because interest is calculated using that larger balance, a greater share of the scheduled principal-and-interest payment generally goes toward interest.
Does the mortgage interest rate change as more of the payment goes toward principal?
Not on a standard fixed-rate mortgage. The rate remains fixed according to the loan terms. What changes is the outstanding principal balance, which affects the dollar amount of interest due within each scheduled payment.
When does more of a mortgage payment begin going toward principal than interest?
There is no single point that applies to every mortgage. The timing depends on the interest rate, original loan amount, loan term, and payment history. The mortgage’s amortization schedule shows when the principal portion becomes larger for that specific loan.
Does escrow reduce the mortgage principal?
No. Amounts collected for property taxes or homeowners insurance through an escrow account are separate from principal repayment. Only the principal portion of the mortgage payment reduces the loan balance.
How can homeowners see how much interest they are paying?
Mortgage statements generally show how payments are applied, while an amortization schedule shows the scheduled division between principal and interest over time. Reviewing the current balance, rate, and remaining term provides additional context.