A mortgage rate is easy to notice. A borrower sees 5%, 6%, or 7% and naturally treats that number as the cost of the loan. But the rate is only one part of the picture.
The actual mortgage interest cost depends on how much is borrowed, how long the balance remains outstanding, and how the loan amortizes over time. Two mortgages with the same rate can produce very different total interest costs if the balances or repayment terms are different.
That distinction matters because homeowners often compare mortgages by rate or monthly payment alone. A more useful comparison looks at the rate together with the loan balance, remaining term, and expected interest over time.
The Rate Tells You How Interest Is Charged, Not the Final Dollar Cost
The mortgage interest rate tells a borrower the rate used to calculate interest under the loan agreement. It is an important number, but it does not tell a homeowner how many dollars of interest will ultimately be paid.
A percentage only becomes a dollar cost when it is applied to a balance.
Consider two homeowners with the same fixed interest rate. One owes $180,000 and the other owes $360,000. Even though the rate is identical, the larger balance gives interest a larger base on which to be calculated.
Time matters too. If one mortgage has 10 years remaining and another has 25, the second loan has many more scheduled payment periods ahead.
This is why a mortgage rate should be treated as a starting point rather than a complete measure of cost. Homeowners who want the broader picture can review How to Reduce Mortgage Interest for the main factors that influence interest over the life of a loan.
Balance and Time Change What the Same Rate Can Cost
The outstanding principal balance is one of the clearest drivers of mortgage interest.
Early in a mortgage, the balance is relatively high. As scheduled payments reduce principal, the amount owed becomes smaller. The fixed interest rate may stay exactly the same, but the dollars of interest due within each payment can change because the balance has changed.
Loan term adds another layer.
A 30-year loan spreads repayment across far more months than a 15-year loan. That can reduce the required monthly principal-and-interest payment, but it also allows the balance to remain outstanding for longer.
This does not mean a shorter term is automatically the right choice for every household. A shorter mortgage generally requires a higher monthly payment, and that higher payment has to fit the rest of the household budget.
The important point is that total interest cannot be understood by looking at the rate alone. The balance tells how much is being financed. The term tells how long repayment is scheduled to continue. The rate determines how interest is charged along the way.
Why More of the Payment Goes to Interest Early in the Mortgage
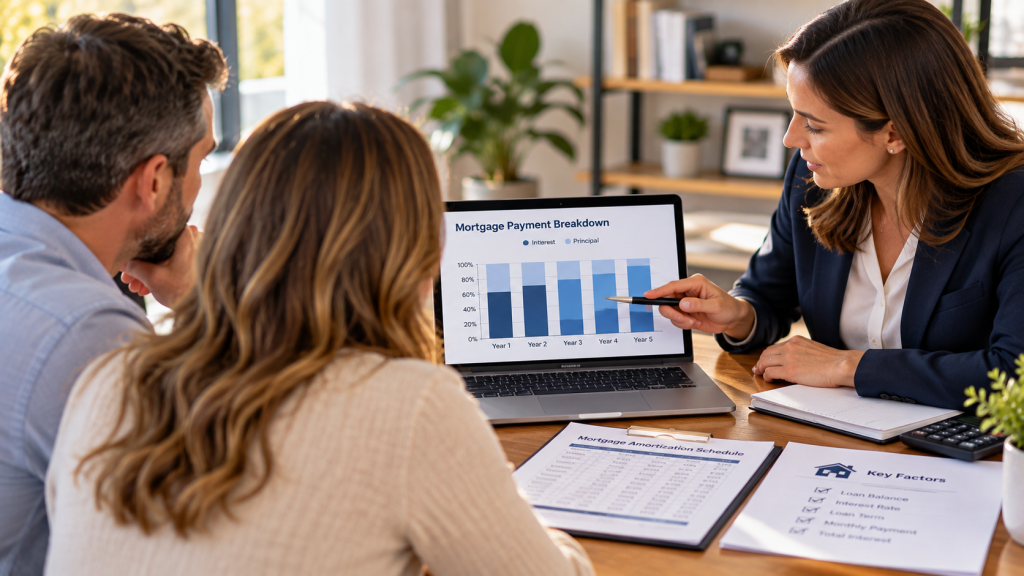
Most fixed-rate mortgages are amortizing loans. The scheduled principal-and-interest payment may remain level, but the way that payment is divided changes over time.
Near the beginning of the loan, the borrower still owes most of the original principal. Because the outstanding balance is higher, the interest portion of the payment is generally higher as well.
As principal is paid down, less interest is due and more of the scheduled payment can go toward principal.
This is sometimes described as if the lender simply “takes all the interest first.” That description can be misleading. The pattern comes from the amortization math: a larger balance produces more interest dollars than a smaller balance at the same rate.
Looking at the mortgage this way makes the cause and effect clearer. The payment is not changing simply because the loan has reached a certain age. The balance itself is changing, and that affects how much interest is calculated.
For this discussion, the key point is simple: the rate may stay fixed while the balance used to calculate interest changes.
A Lower Monthly Payment Does Not Always Mean Lower Interest
Monthly payment matters because it affects cash flow immediately. But it is possible to lower the payment without lowering the total interest cost.
Refinancing is a common example.
A homeowner may replace an existing mortgage with a new loan that has a lower rate. That can reduce the monthly payment. But if the new mortgage also restarts repayment across a fresh 30-year term, the borrower may be extending the amount of time the balance remains outstanding.
That does not make refinancing good or bad by itself. It means the decision should be evaluated using more than the new payment.
A useful comparison asks:
- What is the remaining balance on the current mortgage?
- How much interest is still scheduled under the existing loan?
- What will the new rate and term be?
- What closing costs or fees are required?
- How long is the homeowner likely to keep the new mortgage?
A lower payment may improve monthly cash flow, which can be valuable. But cash-flow relief and mortgage interest savings are not the same result.
Homeowners considering a change to the repayment path can also review What to Calculate Before Paying Off a Mortgage Early for additional context on balances, payoff timing, and projected interest.
Interest Rate, APR, and TIP Measure Different Things
Mortgage documents can show several percentages, and each answers a different question.
The mortgage interest rate is the rate charged under the loan terms.
The annual percentage rate, or APR, is a broader measure of borrowing cost that can include the interest rate and certain other charges associated with obtaining the mortgage.
Total Interest Percentage, or TIP, is different again. TIP expresses the total scheduled interest over the life of the mortgage as a percentage of the loan amount, using the assumptions required for the mortgage disclosure.
These figures should not be treated as interchangeable.
A mortgage can have an annual interest rate that looks modest next to its TIP because TIP reflects scheduled interest over the full repayment period rather than an annual rate.
The important takeaway here is straightforward: the mortgage rate does not tell a homeowner the total interest dollars that may be paid over the life of the loan.
What to Compare When Looking Beyond the Rate
A better mortgage comparison uses the numbers that actually shape the cost from this point forward.
Start with the current principal balance, interest rate, remaining term, and required principal-and-interest payment. Then look at the estimated interest remaining under the existing schedule.
If another option is being considered, compare it using the same categories.
For a refinance, that means reviewing the proposed rate, term, payment, closing costs, and expected interest. For a faster repayment plan, it means looking at how additional principal would change the balance and payoff timing.
The goal is not to make the mortgage more complicated. It is to make the tradeoffs visible.
Using the household’s actual mortgage information makes it easier to compare the current path with another option instead of assuming that a lower rate or lower payment automatically produces a better long-term result.
This comparison is especially useful when a homeowner is deciding whether a change actually reduces borrowing cost or simply shifts the payment schedule. Looking at the same set of numbers before and after the change keeps the comparison consistent and makes it easier to see what is different.
A rate is important. But balance and time determine how much opportunity that rate has to create interest.
For homeowners trying to understand mortgage interest cost, the better question is not simply, “What is my rate?”
It is, “What will this mortgage cost from here if I keep the current path, and what changes if I choose another one?”
Frequently Asked Questions
Can two mortgages with the same interest rate have different interest costs?
Yes. The loan balance, repayment term, remaining time on the mortgage, and payment history can all affect the dollar amount of interest paid. Two loans with the same rate can therefore have very different total interest costs.
Why is the interest portion higher near the beginning of a mortgage?
In a typical amortizing mortgage, the principal balance is highest near the beginning. Because interest is calculated using that larger balance, a larger share of the scheduled payment generally goes toward interest early in the loan.
Does a lower monthly mortgage payment always save interest?
No. A lower payment may come from a lower rate, a longer repayment term, or both. If the term is extended, the loan may remain outstanding for more years. Homeowners should compare total projected interest, the new term, and any costs of changing the loan.
Is APR the same as the mortgage interest rate?
No. The mortgage interest rate is the rate charged on the loan. APR is a broader measure of borrowing cost that can include certain fees and other charges in addition to interest.
What should homeowners compare besides the mortgage rate?
Review the principal balance, remaining term, monthly principal-and-interest payment, estimated remaining interest, and any costs required to change the mortgage. Looking at those figures together gives a clearer picture of the loan’s long-term cost.